

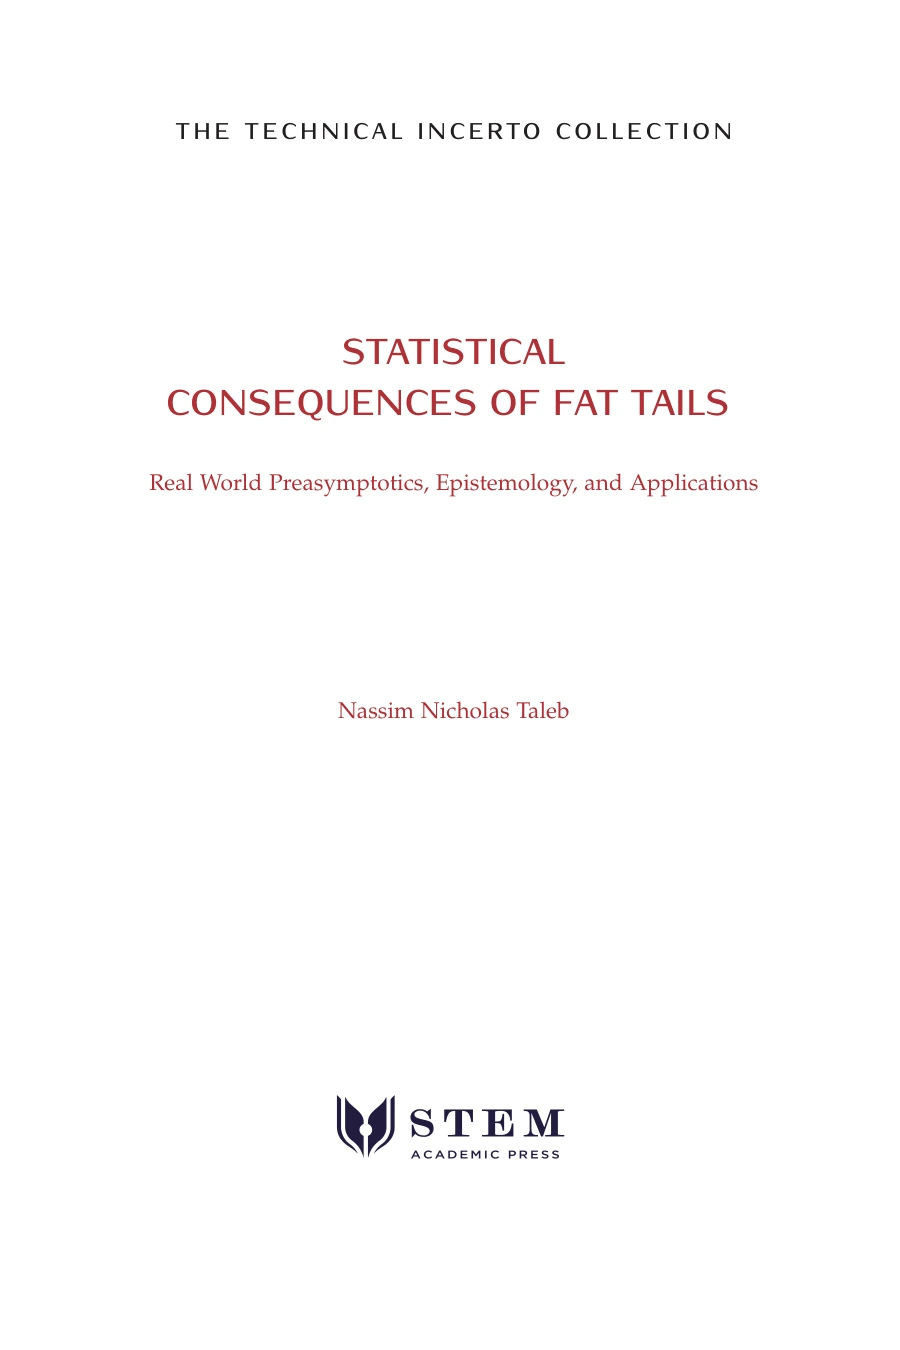
Statistical Consequences of Fat Tails: Real World Preasymptotics, Epistemology, and Applications
Original price was: $5.00.$2.50Current price is: $2.50.

Nassim Nicholas Taleb
Product Specs:
- File Type: PDF
- File Size: 27.3 MB
- Book Language: English
- Total Page Count: 445
- Instant Download
Why Fat Tails Change Everything
Standard statistical education rests on the law of large numbers and the central limit theorem, but Nassim Nicholas Taleb demonstrates that the preasymptotic world—the real world—often behaves very differently. When distributions have fat tails, convergence to normality can be slow or absent, making many conventional estimators, risk measures, and forecasting methods unreliable.
This book provides a rigorous yet accessible exploration of what fat tails mean for practice. Taleb builds from first principles, offering both intuitive explanations and formal analysis. The text distinguishes between thin-tailed and heavy-tailed processes, introduces operational metrics for fat-tailedness, and shows how extreme events dominate aggregate behavior even when they are rare.
From Power Laws to Hidden Risks
The early chapters develop the mathematics of fat tails, including power law classes, subexponential distributions, and stable distributions. Taleb then examines the law of medium numbers—the preasymptotic regime where sample averages are neither fully erratic nor fully convergent. He introduces the concept of hidden risk, explaining why empirical data often mask the likelihood of tail events.
Later sections apply these ideas to forecasting, probability calibration, and decision-making under uncertainty. Case studies and empirical analyses, including diagnostics on the S&P 500, illustrate how fat tails affect market behavior and risk assessment. The book also addresses epistemological pitfalls, such as naive empiricism and the confusion between exposure to a variable and knowledge about it.
Who This Book Is For
This is a technical work aimed at readers who already have some familiarity with probability and statistics. It will be most valuable to quantitative researchers, econometricians, financial risk managers, data scientists, and philosophers of science. The mathematical derivations are substantial, but each section is structured so that nontechnical readers can follow the core arguments through the starred chapters and discussions.
The Technical Incerto Collection provides the formal backbone for ideas that appear in Taleb’s more popular works. Here, the focus is on the mathematics and its implications, with a level of detail suitable for graduate study or professional reference.
What You Can Expect to Learn
- How heavy tails violate assumptions behind common statistical tools.
- Why standard deviation can be misleading under fat tails and what to use instead.
- Operational ways to measure and detect fat-tailedness in data.
- The role of extreme value theory in understanding tail risk.
- How to calibrate probabilities and avoid systematic over- or underestimation of rare events.
- Practical heuristics for decision-making when tail risks dominate.
The book is not a collection of quick fixes. It is a careful re-examination of statistical practice from the ground up, grounded in both theory and real data.
User Reviews
Only logged in customers who have purchased this product may leave a review.
Original price was: $5.00.$2.50Current price is: $2.50.
There are no reviews yet.