

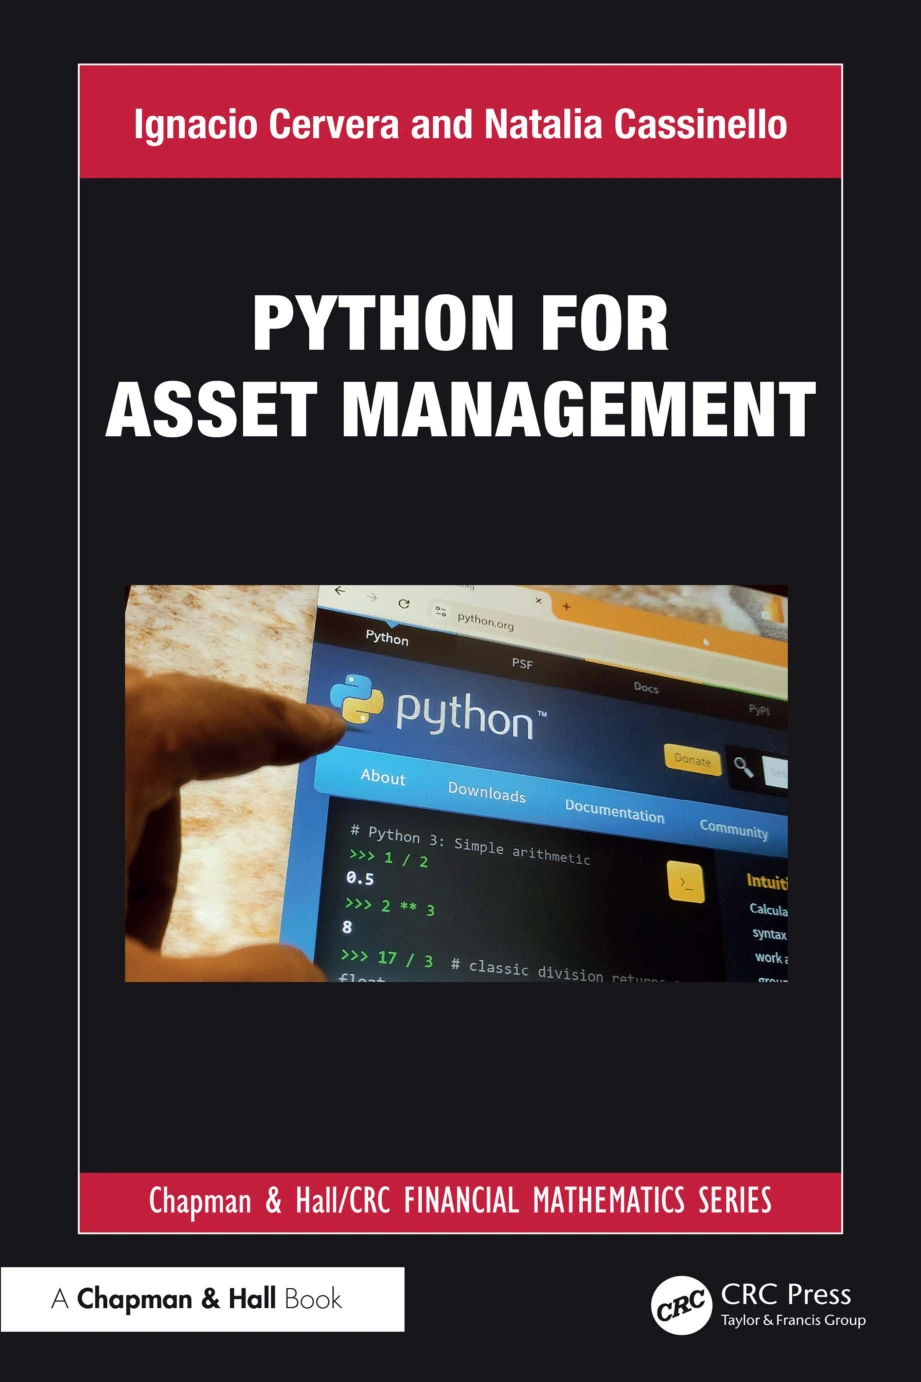
Python for Asset Management
Original price was: $5.00.$2.50Current price is: $2.50.

Ignacio Cervera
Product Specs:
- File Type: PDF
- File Size: 8.1 MB
- Book Language: English
- Total Page Count: 337
- Instant Download
Python for Asset Management: From Spreadsheets to Scalable Models 📊
Asset management is shifting toward automation, transparency, and data-driven decisions. This book is a practical guide for finance professionals who want to use Python to build and test portfolio models themselves—without needing a programming background.
What You’ll Work Through 💻
The material starts with the core Python libraries used in finance: pandas, NumPy, statsmodels, SciPy, PuLP, yfinance, empyrical, and more. From there, it moves into applied tasks across equities, bonds, and performance attribution.
- Market index analysis: retrieve, preprocess, and analyze index data; calculate summary statistics and rolling metrics.
- Equity management: implement Modern Portfolio Theory, the Markowitz model, CAPM, and alternatives; measure management quality and test the efficient markets hypothesis.
- Risk measurement: calculate Value at Risk using historical simulation, parametric methods, and Monte Carlo simulation.
- Bond management: value bonds, build bullet, barbell, and ladder portfolios, and apply immunization and cash flow matching.
- Return attribution: run Brinson–Fachler attribution for equity portfolios and fixed income attribution covering yield curve, duration, credit spread, carry, convexity, selection, and currency effects.
Exercises That Produce Real Deliverables
Across 31 hands-on exercises, you work with real data and executable code. The companion GitHub repository (MIT License) includes all scripts, data pipelines, and results. Each exercise is designed to produce something useful—optimal weights, a risk report, an attribution table—that can support client meetings and investment decisions.
Written for Finance Professionals, Not Programmers
If you are a portfolio manager, risk analyst, student, or investment professional who has relied on Excel and Bloomberg, this book offers a structured path to implementing advanced models in Python. The focus stays on practical asset management workflows rather than abstract theory.
About the Authors
Ignacio Cervera holds a PhD in business administration from Universidad Pontificia Comillas and an MBA from IE-Madrid. He is Professor of Corporate Finance and Portfolio Management & Investments and co-director of the Asset Management Chair at Universidad Pontificia Comillas. Natalia Cassinello holds a PhD in business administration and an executive master’s in behavioral economics from LSE. She is Professor in Finance and ESG and Co-Director of the Asset Management Chair at Universidad Pontificia Comillas, and Deputy Chief Financial Officer at the university.
Why This Book Matters
Quantitative literacy is becoming essential in modern asset management, especially in areas such as sustainable investing and smart beta strategies. This book responds to that shift with a direct, code-first approach that helps readers move from understanding concepts to running their own models.
User Reviews
Only logged in customers who have purchased this product may leave a review.
Original price was: $5.00.$2.50Current price is: $2.50.
There are no reviews yet.