

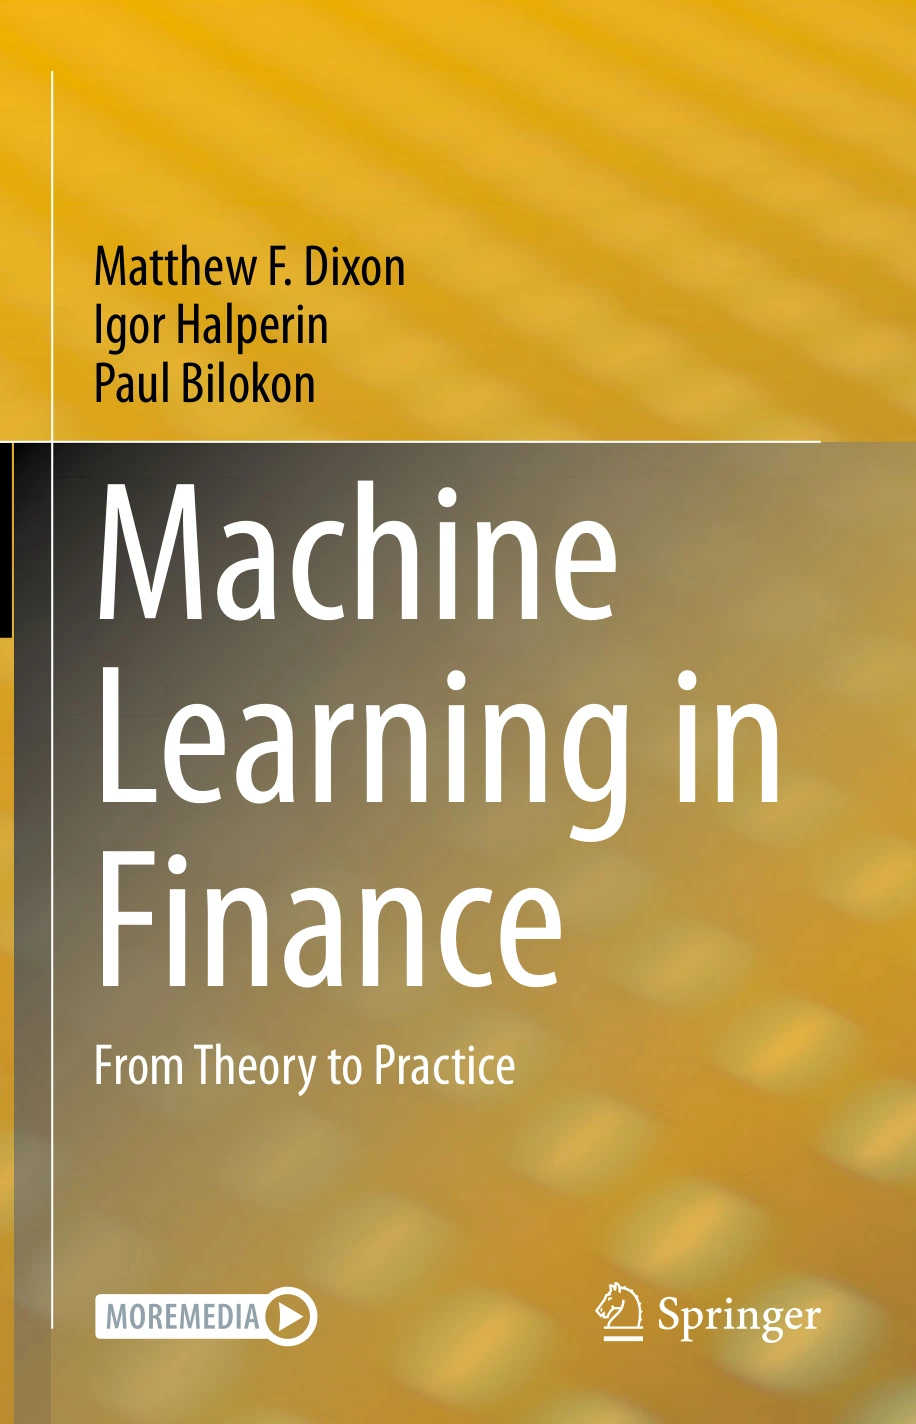
Machine Learning in Finance: From Theory to Practice
Original price was: $13.99.$7.00Current price is: $7.00.

Matthew F. Dixon
Product Specs:
- File Type: PDF
- File Size: 9.5 MB
- Book Language: English
- Total Page Count: 565
- Instant Download
Financial machine learning becomes more useful when its methods are understood alongside the quantitative ideas finance already relies on. Machine Learning in Finance: From Theory to Practice builds that connection, relating statistical learning to financial econometrics, time-series analysis, and stochastic control rather than treating algorithms as black boxes.
Matthew F. Dixon, Igor Halperin, and Paul Bilokon take a mathematically grounded approach, moving from supervised learning to sequential data and, finally, decisions made through reinforcement learning. The result is a demanding textbook for readers who want to understand the reasoning behind financial applications as well as the methods themselves.
Three routes into financial machine learning
The book is organized around three broad areas. It begins with supervised learning for cross-sectional data, including Bayesian approaches, Gaussian processes, and neural networks. It then turns to financial time series and sequence modeling before examining reinforcement learning and decision-making in finance.
Examples connect these ideas to applications such as trading, investment management, derivatives, risk management, and wealth management. Throughout, the authors relate machine-learning models to established statistical and financial methods, giving readers a framework for comparing approaches rather than simply selecting an algorithm by name.
Mathematical foundations, not just algorithms
Regularization, model averaging, forecasting, and model interpretation are among the ideas that help frame the book’s treatment of learning methods. Neural networks and deep learning are considered in relation to familiar models, while the later material explores how reinforcement learning can be used to formulate financial control problems.
Python examples, numerical illustrations, multiple-choice questions, and end-of-chapter exercises accompany the theoretical discussion. Together, they give readers opportunities to work through both the concepts and their application.
Who will find it useful?
This is a technically advanced text intended for graduate students and researchers in financial econometrics, applied statistics, mathematical finance, and related fields, as well as quants and data scientists in quantitative finance. The stated background includes advanced probability and statistics, linear algebra, time-series econometrics, numerical optimization, and Python programming; readers approaching the later reinforcement-learning chapters may also benefit from prior familiarity with investment science.
For readers with that foundation, this book offers a structured way to study financial machine learning in context—linking its mathematical ideas to the modeling and decision problems that arise across quantitative finance.
User Reviews
Only logged in customers who have purchased this product may leave a review.
Original price was: $13.99.$7.00Current price is: $7.00.
There are no reviews yet.