

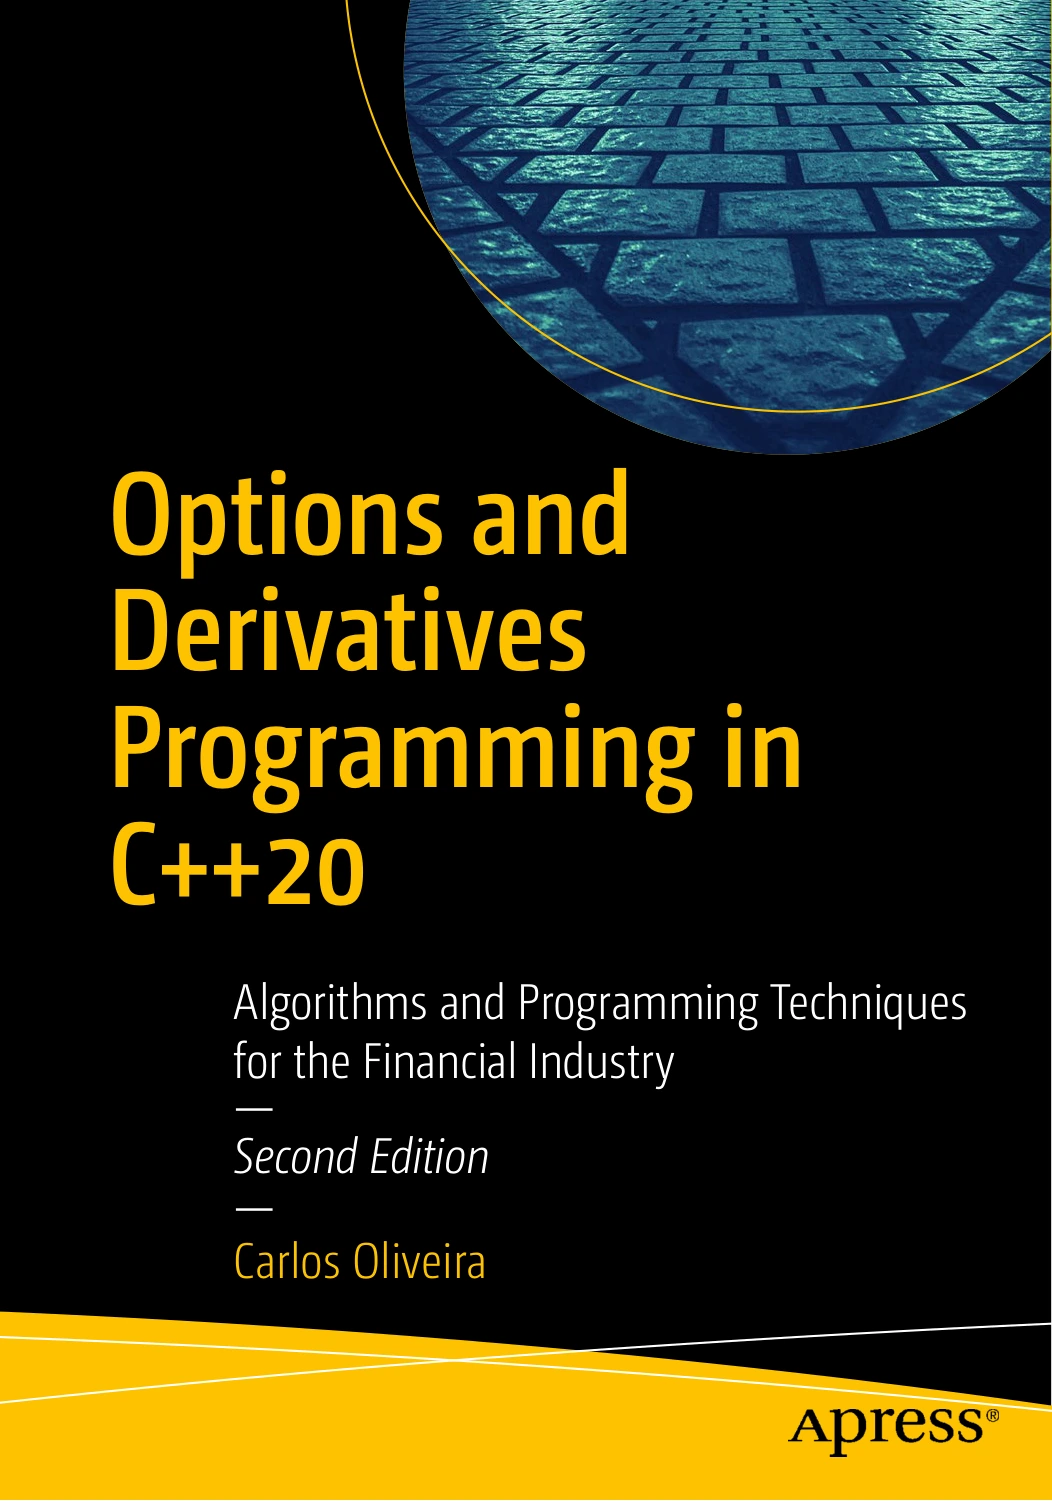
Options and Derivatives Programming in C++20: Algorithms and Programming Techniques for the Financial Industry, Second Edition | Options and Derivatives Programming in C++20
Original price was: $5.00.$2.50Current price is: $2.50.

Carlos Oliveira
Product Specs:
- File Type: PDF
- File Size: 3.9 MB
- Book Language: English
- Total Page Count: 408
- Instant Download
Modern C++ for Options and Derivatives Pricing 💻📈
Financial derivatives demand more than textbook formulas. They require software that can represent contracts, solve pricing equations, simulate market paths, and stay maintainable as models evolve. Options and Derivatives Programming in C++20 is Carlos Oliveira’s practical guide to that intersection, written for developers who want to implement financial algorithms in modern C++ rather than only read about them.
This second edition updates the material for C++20 and keeps the focus on the financial industry: options, derivatives, pricing models, and the programming techniques needed to turn mathematical ideas into working code.
A Structured Path Through Finance and Code
The book starts with options concepts and financial derivatives before building the C++ foundation for larger quantitative projects. From there it examines core algorithms, object-oriented techniques, design patterns for options processing, template-based methods, and the STL. Later sections move into functional programming, linear algebra, numerical analysis, differential equations, and the models used to price options.
From Black-Scholes to Monte Carlo ⚙️
Pricing models are treated as implementation problems, not just equations on a page. Readers encounter binomial models, American-style options, the Black-Scholes model and its numerical solution, Monte Carlo methods, and common probability distributions. The final chapters look at using C++ libraries for finance, including Boost-based work such as creating histograms and computing solutions for Black-Scholes equations.
What Makes This Edition Useful
- C++20 perspective: the second edition brings the code and techniques up to date with modern language features.
- Finance-first algorithms: examples and structures are chosen around derivatives and options workflows.
- Design and maintainability: object-oriented techniques, design patterns, templates, and smart pointers help keep financial code organized.
- Numerical grounding: linear algebra, differential equations, and numerical methods support the pricing models.
- Practical library use: coverage of the STL and external C++ libraries shows how to build on established tools rather than starting from zero.
Who Will Get the Most From It
The material suits C++ developers moving into quantitative finance, quantitative analysts who want stronger implementation skills, and students or professionals building pricing tools. A basic working knowledge of C++ will help, though the book revisits core language techniques as they apply to options and derivatives programming. Readers looking for a purely theoretical finance text may find the emphasis here is different: the goal is to understand the models well enough to implement them.
Why It Belongs on a Quant Developer’s Shelf
Many resources separate financial theory from software craft. This one keeps them together, showing how C++ algorithms, data structures, and numerical routines work in service of derivatives pricing. If you want to move from formulas to functioning models, this second edition offers a focused route through both the language and the financial ideas.
User Reviews
Be the first to review “Options and Derivatives Programming in C++20: Algorithms and Programming Techniques for the Financial Industry, Second Edition | Options and Derivatives Programming in C++20”
You must be logged in to post a review.
Original price was: $5.00.$2.50Current price is: $2.50.
There are no reviews yet.